
Retirement planning involves more than simply saving money for the future. Building an investment portfolio that can generate a regular income after retirement is equally important. Factors such as inflation, healthcare expenses, lifestyle choices and life expectancy can significantly affect how much money you will need in your later years.
One option available to mutual fund investors is a Systematic Withdrawal Plan (SWP). It allows investors to withdraw a fixed amount from their mutual fund investments at regular intervals, such as monthly or quarterly, while keeping the remaining balance invested. According to a ClearTax report, SWPs are commonly used by retirees who want a regular income from their accumulated investments.
How to Calculate Your Retirement Corpus
The first step towards retirement planning is deciding what kind of lifestyle you want after leaving the workforce. Your family responsibilities, health needs and expected living expenses should all be considered.
Next, compare your current income and expenses with the amount you expect to spend after retirement. Remember that inflation can gradually reduce the purchasing power of your savings, making it important to account for rising costs over time.
Starting early can make a significant difference because investments have more time to benefit from compounding. Investors can consider different asset classes, including bank deposits, bonds, equities, cash equivalents and real estate, depending on their financial goals, age and risk tolerance.
Government-backed savings options such as the Public Provident Fund (PPF), Employees’ Provident Fund (EPF), National Pension System (NPS) and National Savings Certificate (NSC) may also form part of a retirement strategy, subject to their respective rules and tax provisions.
It is equally important to maintain a separate emergency fund and suitable insurance coverage. These measures can help prevent unexpected expenses from eating into retirement savings.
One commonly used rough estimate suggests building a retirement corpus equal to 300 times your current monthly expenses. However, this is only a broad guideline and should be adjusted for inflation, retirement duration, expected returns and individual circumstances.
How Much Should You Invest to Receive ₹50,000 a Month?
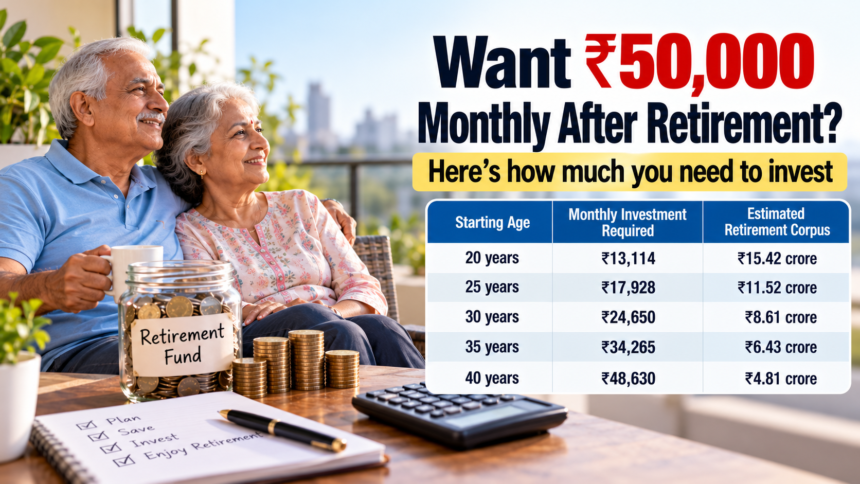
The amount you need to invest depends largely on when you begin saving and the returns your investments generate. The following estimates from the supplied calculations illustrate how monthly investment requirements change with age.
The figures assume retirement at age 60, an estimated life expectancy of 85 years, annual inflation of 6% and an assumed investment return of 12% during the accumulation period. They also assume a 6% return during retirement and no other retirement savings or investments.
| Starting age | Monthly investment required | Estimated retirement corpus |
|---|---|---|
| 20 years | ₹13,114 | ₹15.42 crore |
| 25 years | ₹17,928 | ₹11.52 crore |
| 30 years | ₹24,650 | ₹8.61 crore |
| 35 years | ₹34,265 | ₹6.43 crore |
| 40 years | ₹48,630 | ₹4.81 crore |
These estimates show that beginning early can reduce the monthly amount required to build a retirement fund. Someone who starts investing at 20 has a longer period to accumulate wealth than someone who begins at 40.
The figures are illustrative rather than guaranteed outcomes. Actual results will depend on investment performance, fees, taxes, withdrawal amounts and changes in living expenses.
Why Starting Early Can Make a Difference
Investing over a longer period gives compounding more time to work. Even if an investor begins with a relatively modest monthly contribution, consistent investing can help build a substantial corpus over several decades.
Those who start later may need to invest significantly more each month to reach a similar retirement goal. They may also need to review their retirement age, expected spending and investment strategy to determine what is financially realistic.
Investors should avoid relying entirely on assumed returns. Market-linked investments can fluctuate, and actual returns may be lower or higher than projected. A balanced portfolio, regular reviews and realistic expectations are important when planning for retirement income.
Disclaimer: This article is intended for educational and informational purposes only and should not be treated as financial or investment advice. The investment amounts, expected returns and retirement corpus figures are illustrative estimates and are not guaranteed. Actual outcomes depend on market performance, inflation, taxes, fees, withdrawal requirements and individual financial circumstances. Consult a qualified financial adviser before making investment decisions.