
Buying a house is a major financial commitment that requires careful planning. Apart from the property’s price, prospective homeowners need to consider their monthly income, savings, down payment, loan tenure and existing financial obligations before applying for a home loan.
Choosing a loan that is too large can put pressure on household finances. If monthly instalments become difficult to manage, borrowers may struggle to meet other expenses, potentially affecting their credit score and overall financial health.
So, how much monthly salary is required to purchase a property worth ₹50 lakh, ₹75 lakh or ₹1 crore? The answer depends on the loan amount, interest rate and the proportion of income available for repayments.
How Much Monthly Salary Is Required for a Home Loan?
Gaurav Garg, Head of Research at Lemonn, has outlined the estimated EMI and income requirements for three different property prices, assuming a 20% down payment and a 20-year loan at an illustrative interest rate of 8.5%.
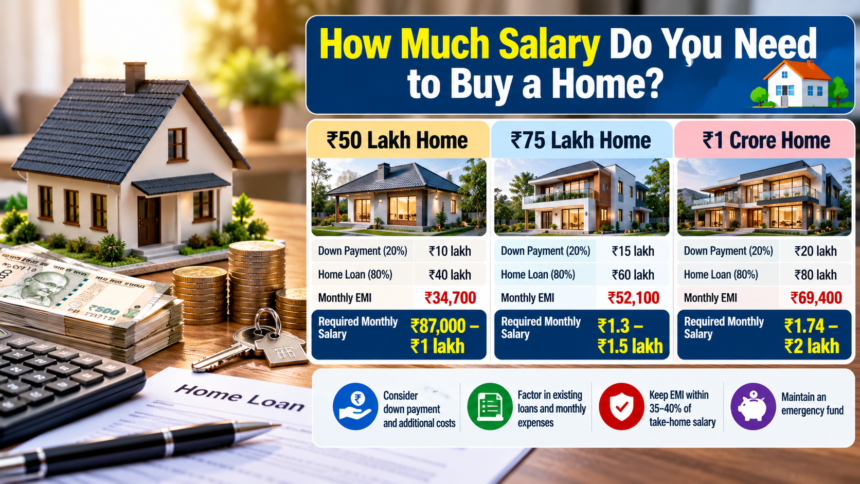
According to these estimates, the monthly EMI for a ₹50 lakh property would be approximately ₹34,700. For a ₹75 lakh home, the EMI would rise to around ₹52,100, while purchasing a ₹1 crore property would involve a monthly repayment of approximately ₹69,400.
Garg explained that buyers should ideally keep their home loan EMI within 35–40% of their monthly take-home salary. Based on this approach, the suggested income requirements are as follows.
| Property price | Down payment (20%) | Loan amount (80%) | Monthly EMI | Suggested monthly take-home salary |
|---|---|---|---|---|
| ₹50 lakh | ₹10 lakh | ₹40 lakh | ₹34,700 | ₹87,000–₹1 lakh |
| ₹75 lakh | ₹15 lakh | ₹60 lakh | ₹52,100 | ₹1.3–₹1.5 lakh |
| ₹1 crore | ₹20 lakh | ₹80 lakh | ₹69,400 | ₹1.74–₹2 lakh |
Note: These figures are estimates based on a 20-year loan at 8.5% interest. The suggested income ranges assume that the EMI accounts for approximately 35–40% of monthly take-home pay. Actual repayments and eligibility may vary.
Additional Costs to Consider Before Buying a House
The down payment is not the only expense buyers need to prepare for when purchasing a property. Several additional charges can increase the overall cost of homeownership.
These expenses may include stamp duty, property registration, interior work, housing society charges, where applicable, and other related costs. Buyers should calculate these expenses separately rather than using their entire savings for the down payment.
It is also important to maintain an emergency fund. Having sufficient savings can help households manage unexpected expenses while continuing to pay their monthly home loan instalments.
How Existing Loans Affect Home Loan Affordability
A borrower’s salary alone does not determine how much home loan they can comfortably afford. Existing EMIs, household expenses, dependent-related costs and other financial commitments must also be considered.
For example, someone earning a relatively high salary may still face repayment difficulties if a significant portion of their income goes towards other loans and regular expenses.
Garg emphasised that buyers should compare interest rates and loan terms carefully. Even a small change in the interest rate can affect the overall repayment amount over the loan period.
He also noted that banks may approve different loan amounts depending on an applicant’s eligibility. However, loan approval does not necessarily mean that the repayment will fit comfortably into the household budget.
How Much of Your Salary Should Go Towards EMI?
Ideally, borrowers should aim to keep their total monthly loan repayments within 35–40% of their take-home income. Those approaching the upper end of this range should assess their finances particularly carefully.
A realistic home-buying budget should leave enough money for essential household expenses, insurance, retirement savings, emergency funds and other financial goals.
Ultimately, purchasing a home is financially sensible when the EMI remains manageable throughout the loan tenure. Planning ahead and accounting for both upfront and recurring expenses can help buyers choose a property without placing unnecessary pressure on their finances.
Disclaimer: This article is intended for general informational purposes only and should not be considered financial advice. The EMI and salary figures are illustrative estimates. Actual home loan eligibility, interest rates, repayment amounts and affordability depend on the lender’s terms, the borrower’s income, credit profile, existing liabilities and individual financial circumstances. Buyers should assess their financial position and consult a qualified financial adviser before making borrowing decisions.