
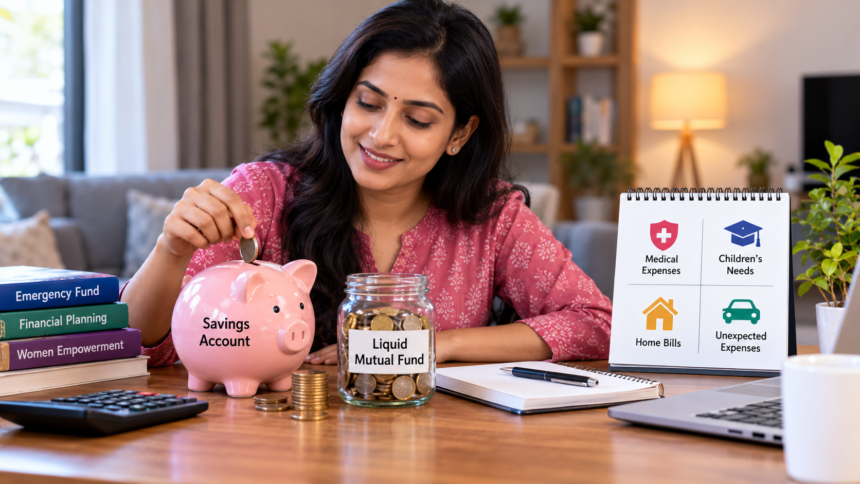
Building an emergency fund is an important part of financial planning, particularly for women who may need to handle unexpected household or personal expenses. Medical costs, children’s requirements, urgent bills or other unforeseen expenses can arise without warning.
A savings account is the most common place to keep emergency money. However, another option is to keep a portion of the fund in a liquid mutual fund while maintaining enough cash in the bank for immediate requirements.
What Is a Liquid Fund?
A liquid fund is a type of debt mutual fund that generally invests in short-term money market instruments with maturities of up to 91 days.
These funds are designed for short-term financial needs and aim to provide returns while keeping the investment relatively accessible. However, unlike a bank fixed deposit, the returns from a liquid mutual fund are not fixed or guaranteed.
How Much Should You Keep in an Emergency Fund?
The amount required will depend on an individual’s regular expenses. For example, if a woman’s monthly expenditure is around ₹30,000, she could target an emergency fund of approximately ₹1.80 lakh to cover six months of expenses.
The entire amount does not necessarily have to remain in a savings account. A portion can be kept readily available in the bank, while surplus funds can be invested in a liquid fund.
This approach can allow the savings account balance to handle regular and immediate expenses, while units of the liquid fund can be redeemed if a larger amount is required. Redemption is generally available on business days, and the proceeds are often credited to the linked bank account by the next business day.
Is Liquid Fund Money Available Immediately?
Liquid funds should not be treated as an instant source of cash in every situation. The redemption proceeds may not reach the bank account immediately for every scheme.
However, certain eligible investors and schemes provide an instant redemption facility. Where available, the instant withdrawal limit may be ₹50,000 or 90% of the folio value, whichever is lower. This facility is not compulsory for every liquid fund, so investors should check the specific scheme before relying on it for emergencies.
Liquid Funds Do Not Guarantee Higher Returns Than FDs
Liquid funds should not be selected solely on the assumption that they will provide better returns than fixed deposits. The returns from mutual funds depend on market interest rates and the securities held by the scheme.
In comparison, the interest rate on a fixed deposit is determined by the bank when the deposit is booked.
For an emergency fund, easy access to money and financial safety should remain the main considerations rather than simply looking for higher returns. Since liquid funds are mutual fund investments, their returns are not guaranteed.
Before putting emergency savings into a liquid fund, investors should carefully check the scheme’s expenses, redemption conditions, tax treatment and withdrawal facilities.
Disclaimer: This article is intended for general informational purposes and should not be considered investment or financial advice. Mutual fund investments are subject to market risks, and returns are not guaranteed. Investors should review the relevant scheme documents, costs, taxation and redemption terms and consider their individual financial requirements before making an investment decision.