
With medical expenses continuing to put pressure on household budgets, many health insurance policyholders are considering top-up and super top-up plans to add protection beyond their regular health cover.
Both types of policies provide additional coverage after a specified deductible is reached, but they differ in the way that deductible is calculated. Arun Ramamurthy, co-founder of Staywell.Health, said understanding this difference is important when selecting additional health insurance coverage.
How Top-Up and Super Top-Up Plans Work
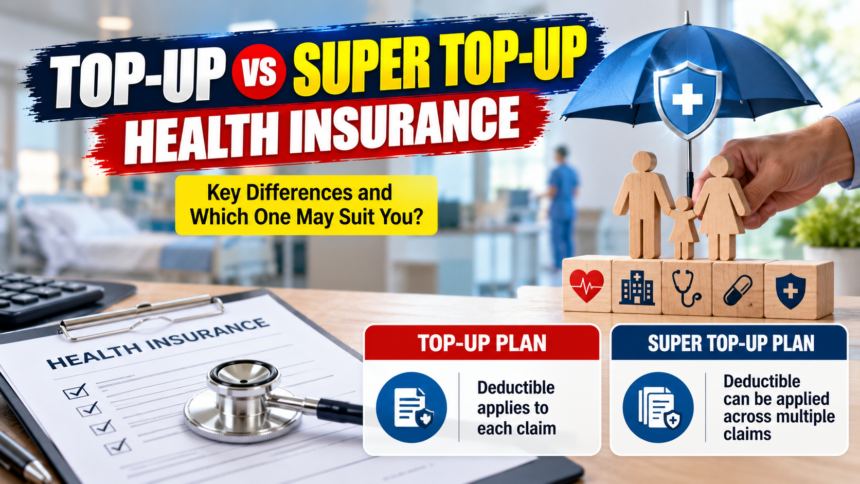
A regular top-up health insurance policy generally applies the deductible separately to each claim.
For example, suppose a person has a base health insurance policy of Rs 5 lakh and a Rs 20 lakh top-up policy with a Rs 5 lakh deductible. If the person is hospitalised twice during the same policy year, with the first bill amounting to Rs 3 lakh and the second costing Rs 4 lakh, neither individual claim crosses the Rs 5 lakh deductible. Therefore, the top-up policy may not provide a payout, depending on its terms and conditions.
A super top-up policy follows a different structure. It can consider eligible medical expenses from multiple claims during the policy year.
Using the same example, the two hospitalisation expenses would add up to Rs 7 lakh. After applying the Rs 5 lakh deductible, Rs 2 lakh could potentially be covered under the super top-up policy, subject to the applicable policy conditions.
“The key difference between a top-up and a super top-up lies in the way the deductible is calculated. While a regular top-up typically considers the deductible against individual claims, a super top-up can aggregate eligible expenses across multiple claims during the policy period,” Ramamurthy said.
When Can Each Policy Be Considered?
The difference in deductible calculation can be relevant for people or families who want additional protection against multiple hospitalisations during the same policy year.
A regular top-up may be considered when the primary concern is an individual hospitalisation involving expenses above the deductible. A super top-up, on the other hand, can take multiple eligible claims into account when calculating whether the deductible has been crossed.
The suitability of either option ultimately depends on the policyholder’s coverage requirements and the specific terms of the policy.
Factors to Check Before Buying
Premium should not be the only factor when comparing top-up and super top-up health insurance plans. Policyholders should examine the deductible structure and sum insured carefully, along with exclusions, waiting periods, co-payment requirements and room-rent restrictions.
It is also important to understand which medical expenses count toward the deductible and whether the policy permits expenses from multiple claims to be aggregated.
Reviewing these conditions in detail can help policyholders understand how the additional cover would work when they actually need to make a claim.
Disclaimer: This article is intended for general informational purposes and should not be considered insurance or financial advice. Policy features, exclusions, deductibles and claim conditions can vary between insurers and plans. Readers should carefully review the policy wording and applicable terms before purchasing health insurance.