
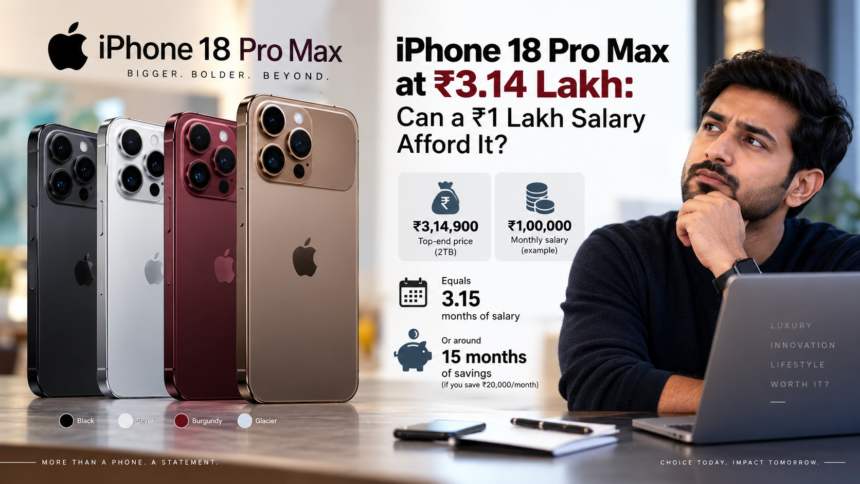
Apple’s latest iPhone 18 Pro and iPhone 18 Pro Max are now available in India from Friday, September 18. While the new models come with premium price tags, the bigger question for buyers earning ₹1 lakh a month is whether purchasing such an expensive smartphone fits comfortably within their finances.
The iPhone 18 Pro is priced from ₹1,64,900 for the 256GB variant and goes up to ₹3,14,900 for the 2TB version. The iPhone 18 Pro Max starts at ₹1,79,900. Both models are available in Burgundy, Glacier, Silver and Black.
Bank offers and exchange benefits may lower the effective purchase price, but the top-end models can still represent a major discretionary expense for someone earning ₹1 lakh every month.
A ₹3 Lakh iPhone Could Equal More Than a Year of Savings
Prasenjit Paul, Fund Manager at 129 Wealth & Head of Research at Paul Asset, said the affordability of a premium smartphone should be considered in relation to a person’s savings rather than simply their monthly income.
According to Paul, a ₹3 lakh smartphone may appear to cost around three months of salary for someone earning ₹1 lakh a month. However, the picture changes significantly when the purchase is compared with actual monthly savings.
For example, if the person saves around ₹20,000 each month after paying rent, household expenses, EMIs and other commitments, a ₹3 lakh phone would represent roughly 15 months of savings.
| Financial Factor | ₹1 Lakh Monthly Salary Example |
|---|---|
| Monthly income | ₹1,00,000 |
| iPhone 18 Pro Max top-end price | ₹3,14,900 |
| Phone cost as months of salary | 3.15 months |
| Monthly savings | ₹20,000 |
| Phone cost in months of savings | ~15.7 months |
| Potential impact of stopping SIPs | Investment goals could be delayed |
| Potential impact of credit-card debt | Interest and charges could increase the cost |
| Key affordability factors | Emergency fund, debt, investments and financial goals |
Paul said the purchase can therefore be considered a significant lifestyle expense, although the price alone does not determine whether it is financially appropriate for an individual.
He recommends ensuring that an emergency fund is already in place, high-cost debt is avoided and regular investments and important financial goals can continue after the purchase.
What Could You Have to Give Up?
The affordability of the iPhone should not be measured only by whether the buyer can make the payment at the time of purchase. The more important consideration is how the expense affects the rest of the person’s finances.
If buying the phone requires using emergency savings, stopping SIP investments for several months, taking on credit-card debt or delaying an important goal such as a home down payment, the purchase could put additional pressure on the buyer’s finances.
On the other hand, someone who has adequate financial reserves and can purchase the phone without disrupting investments, savings or major financial plans may have enough financial flexibility to spend on a premium product.
As Paul explained, affordability depends on the effect of the purchase on the overall financial position rather than simply whether the monthly salary is sufficient to cover the price.
Is EMI a Better Option for the iPhone 18 Pro Max?
The payment method should be considered only after establishing that the phone itself is affordable, according to Paul.
Paying the entire amount upfront eliminates a future monthly payment commitment. A genuine no-cost EMI, meanwhile, can spread the cash outflow over several months if the buyer already has enough money available.
However, buyers should carefully check the terms before choosing EMI. Processing fees, GST, interest or other charges may apply, and some EMI options could also mean losing an upfront discount or cashback benefit.
The bigger issue is using EMI simply to make a ₹3 lakh smartphone appear affordable. Dividing the cost into smaller monthly instalments does not reduce the actual price; it only spreads the payments over time.
If a buyer needs a long EMI tenure to fit the phone into their monthly budget, or the EMI would reduce their ability to save and invest, waiting to build the required funds or choosing a more affordable model may be worth considering.
The basic principle is that a buyer should be able to afford the product before financing it, rather than relying on financing to make the purchase appear affordable.