
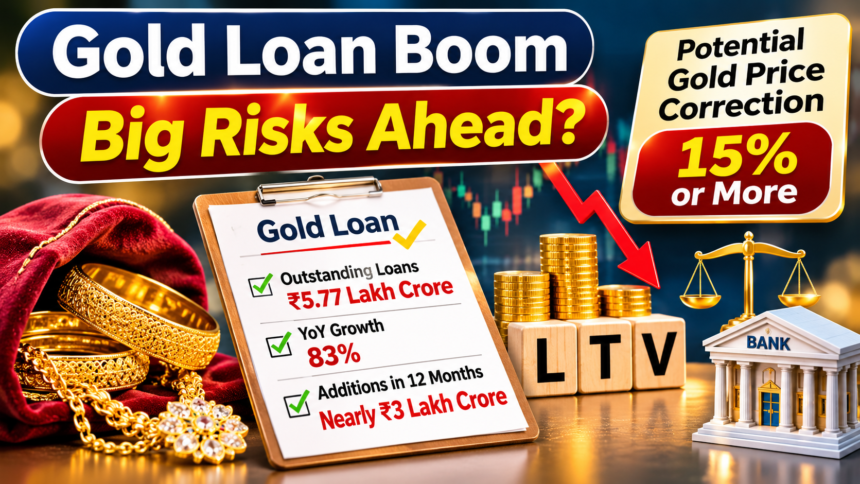
India’s gold loan market has expanded rapidly, with the total value of outstanding loans against pledged gold jewellery reaching ₹5.77 lakh crore. However, the recent correction in gold prices has raised concerns about the value of collateral held by banks and non-banking financial companies (NBFCs).
The growing exposure is attracting attention because a further decline in gold prices could reduce the security backing these loans. The risk is particularly important for lenders that have extended loans at relatively high loan-to-value (LTV) ratios.
In a post on X, Deepak Shenoy highlighted that bank gold loans had increased by 83% year-on-year to ₹5.77 lakh crore. Nearly ₹3 lakh crore was added to outstanding gold loans over the last 12 months. He cautioned that a further correction of around 15% in gold prices could create challenges because of the substantial increase in lending against gold.
The concern comes after a recent fall in bullion prices. According to the figures provided, 24-carat gold was trading at ₹1,38,481 per 10 grams, while MCX December gold futures declined 7.9% in October to approximately ₹1,38,419 per 10 grams.
How Would a 15% Fall in Gold Prices Affect Gold Loans?
A further 15% decline in gold prices would lower the market value of jewellery pledged as collateral with banks and NBFCs.
For example, if gold is priced at ₹1,38,481 per 10 grams, a 15% reduction would bring its indicative value down to around ₹1,17,709 per 10 grams.
This would reduce the value of the security held by lenders, even if the borrower’s outstanding loan amount remained unchanged. Consequently, the loan-to-value ratio would increase.
LTV represents the percentage of a pledged asset’s value covered by the loan. A lower ratio provides lenders with a bigger safety margin if gold prices decline.
Shreepal Doshi, senior analyst covering NBFCs at Equirus Securities, said most gold loan companies currently maintain LTV ratios of approximately 60% to 70%. Lenders operating in the 60%–65% range are generally considered to have a more comfortable buffer.
For instance, a loan initially issued at 65% of the pledged gold’s value would have an effective LTV of approximately 76.5% following a 15% fall in gold prices, assuming the outstanding loan remains unchanged.
Doshi shared the following LTV figures for major gold loan companies:
| Lender | LTV Ratio |
|---|---|
| Muthoot Finance | 64% |
| Manappuram Finance | 65.6% |
| Fedbank Financial Services | 68% |
| IIFL Finance | 70% |
| Capri Global Capital | 73.35% |
According to Doshi, Capri Global Capital’s LTV ratio is relatively less comfortable compared with the lower ratios reported for some other lenders.
Will Borrowers Need to Repay Loans or Pledge More Gold?
A fall in gold prices does not automatically require borrowers to immediately repay a portion of their existing loans or deposit additional jewellery. The actual impact depends on the loan agreement, the lender’s policies, applicable LTV requirements and the repayment structure.
However, a prolonged decline in gold prices could reduce the amount customers are eligible to borrow against the same quantity of jewellery. It may also weaken the collateral protection available to lenders if borrowers fail to repay their loans.
Ponmudi R, founder and CEO of Enrich Money, said falling gold prices could reduce the value of pledged collateral and restrict borrowing capacity for new customers. Loans that were originally approved at higher LTV ratios could also face a smaller security cushion.
Are Gold Loan Companies Facing Higher Financial Risks?
Doshi indicated that a sharp decline in gold prices could lead to higher non-performing assets (NPAs) and credit costs for lenders. However, he did not expect gold prices to fall by 20%–25% from current levels under the prevailing macroeconomic conditions.
The high liquidity of gold provides some protection to lenders, as pledged jewellery can be sold through established recovery channels if borrowers default. Nevertheless, falling prices are not the only challenge facing gold loan companies.
Competition has also put pressure on lending returns. According to Doshi, gold loan yields have declined to 75–79 basis points per month from the earlier range of 100–105 basis points. At the same time, operating expenses remain elevated, creating additional pressure on profitability.
The rapid expansion of gold-backed lending therefore brings risks for both borrowers and financial institutions. Customers may find it harder to obtain larger loans against the same quantity of jewellery, while lenders will need to maintain careful lending standards, monitor collateral values and manage their LTV ratios.
Gold Loan Market: Key Figures and Potential Risks
| Parameter | Details |
|---|---|
| Outstanding gold loans | ₹5.77 lakh crore |
| Year-on-year growth | 83% |
| Additional loans over the past 12 months | Nearly ₹3 lakh crore |
| Potential gold price correction highlighted | 15% or more |
| Gold price reference | December 2025 levels, as mentioned by Shenoy |
| Main concern | Falling gold prices could reduce the value of collateral backing loans |
Disclaimer: This article is for informational purposes only and is based on the figures, expert comments and market details provided. Gold prices, loan-to-value ratios and financial conditions may change. The information should not be treated as investment or borrowing advice. Readers should consult qualified financial professionals before making financial decisions.