
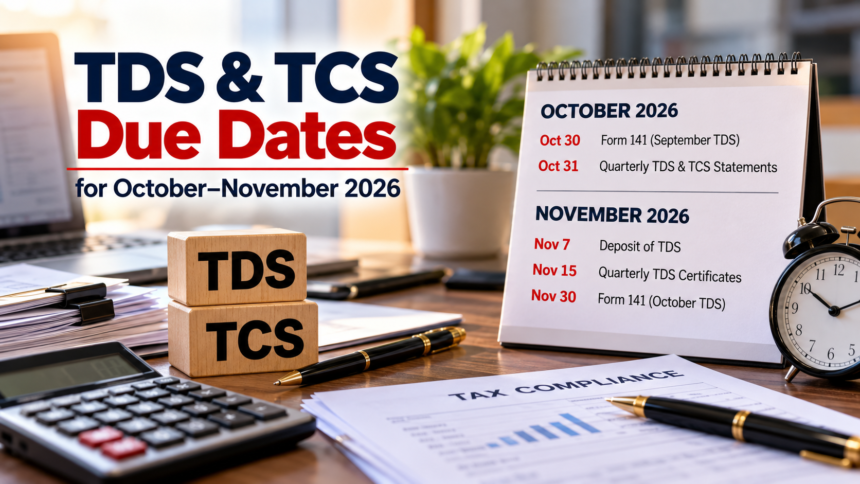
Businesses, deductors and tax collectors have several important Tax Deducted at Source (TDS) and Tax Collected at Source (TCS) compliance deadlines to meet in October and November 2026. These include quarterly statements for the July-September quarter, monthly tax deposits, TDS certificates and challan-cum-statements for specified transactions.
The deadlines fall during the first full tax year under the Income-tax Act, 2025, which introduces revised form numbers for several TDS and TCS filings. Tax professionals have advised businesses to understand the updated requirements, select the correct forms and complete submissions on time to avoid late fees and other compliance-related consequences.
October 2026: Important TDS and TCS Deadlines
October 30: Form 141
The challan-cum-statement for TDS deducted during September on specified transactions must be filed by October 30. These transactions include certain property purchases and rent payments. Deductors should check the applicable provisions and submit the statement within the prescribed period.
October 31: Quarterly TDS and TCS Statements
The quarterly TDS and TCS statements for the July-September 2026 quarter are due on October 31. The applicable forms include:
- Form 138: TDS on salary payments, corresponding to the earlier Form 24Q.
- Form 140: TDS on payments other than salary made to residents, corresponding to the earlier Form 26Q.
- Form 144: TDS on payments to non-residents, corresponding to the earlier Form 27Q.
- Form 143: TCS statement, corresponding to the earlier Form 27EQ.
Deductors and collectors should verify which form applies to their transactions before submitting their quarterly statements.
November 2026: TDS Deposit and Certificate Deadlines
November 7: Deposit of TDS
TDS deducted during October must generally be deposited with the government by November 7, subject to applicable exceptions. Businesses should reconcile their deductions and ensure that the amounts are deposited within the required timeframe.
November 15: Issue of Quarterly TDS Certificates
Deductors must also meet the deadline for issuing TDS certificates for the July-September quarter. Under the revised framework described in the source material, Form 131 replaces the earlier Form 16A for certificates relating to non-salary payments.
November 30: Form 141
The challan-cum-statement for TDS deducted during October on specified transactions must be filed by November 30. Deductors should check the transactions covered by the applicable provisions and complete the filing before the deadline.
What Should Deductors Check Before Filing?
Mehta advised deductors to determine whether a transaction falls under the Income-tax Act, 1961, or the Income-tax Act, 2025, before choosing the relevant form. The applicable framework depends on the transaction date.
Missing TDS or TCS statement deadlines can result in a late fee of ₹200 per day. Interest and penalties may also apply, depending on the circumstances and the relevant provisions.
To avoid compliance issues, businesses should reconcile the tax deducted or collected, deposit the amounts within the prescribed timelines, use the appropriate forms and issue TDS certificates when required.
Since the revised framework includes changes to form numbers and filing requirements, deductors should verify the latest official instructions before submitting their returns or statements.
Disclaimer: This article is intended for general informational purposes only and is based on the details provided in the source material. Tax deadlines, forms, fees and other compliance requirements may depend on the applicable law, transaction date and official notifications. Deductors and tax collectors should consult the latest guidance from the Income Tax Department or a qualified tax professional before taking action.