
Employees planning to withdraw money from their Provident Fund (PF) accounts should pay attention to the tax rules applicable to their withdrawals. According to the information provided, Form 121 will replace Forms 15G and 15H for claiming tax deducted at source (TDS) relief from the 2026-27 tax year.
The Employees’ Provident Fund Organisation (EPFO) allows members to withdraw their accumulated PF savings, subject to the applicable rules. While withdrawals made at retirement may qualify for tax exemption under certain conditions, withdrawing funds before completing the required service period can have tax implications. Understanding the relevant forms and eligibility requirements can help employees manage their tax obligations.
Form 121 to Replace Forms 15G and 15H
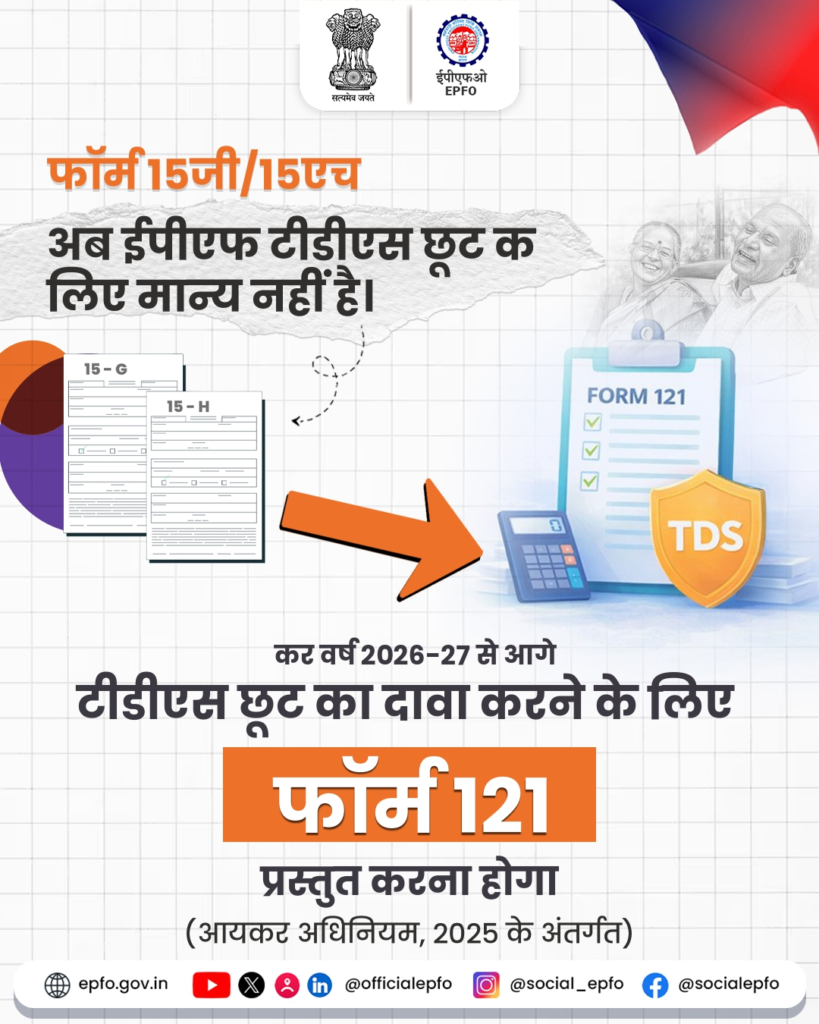
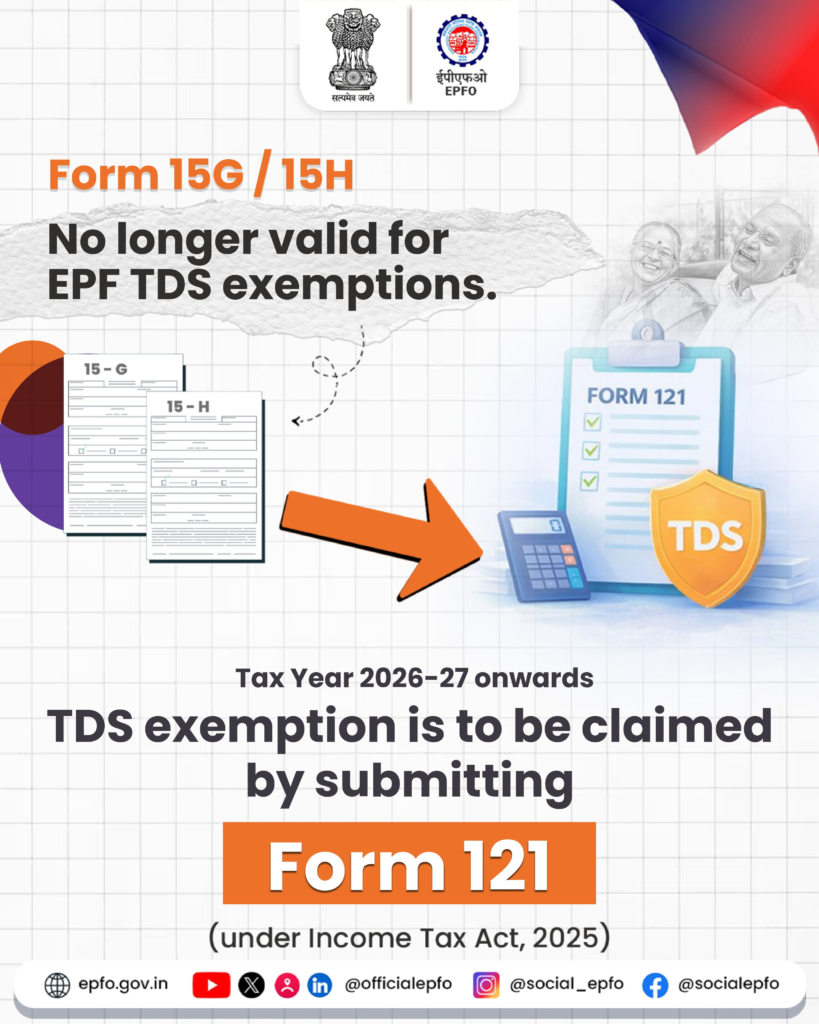
Under the reported changes, EPFO members seeking relief from TDS on eligible PF withdrawals will need to submit Form 121 from the 2026-27 tax year. Forms 15G and 15H will no longer be used for this purpose.
Previously, the form required depended on the applicant’s age and eligibility. Form 15G was generally used by eligible individuals below 60 years of age, while eligible senior citizens used Form 15H.
The introduction of a single form is intended to simplify the declaration process by bringing these applications under one format.
When Is TDS Applicable to PF Withdrawals?
Tax rules may require TDS when an employee withdraws PF savings before completing five years of continuous service. According to the information provided, withdrawals exceeding Rs 50,000 may attract TDS at a rate of 10%, subject to the applicable conditions.
However, the actual tax treatment depends on factors such as the amount withdrawn, the employee’s service history and the applicable tax provisions. Certain exceptions and alternative rates may apply in specific circumstances.
Employees should therefore check the relevant rules before submitting a PF withdrawal request to understand whether TDS will be deducted.
How Can Employees Claim TDS Relief?
Eligible EPFO members can submit the prescribed declaration form when requesting a withdrawal, provided they meet the applicable conditions for relief from TDS.
If tax has already been deducted, the employee may be able to claim credit for the TDS while filing an income tax return. The final tax liability will depend on the individual’s income, eligibility and applicable tax rules.
Before submitting Form 121 or initiating a PF withdrawal, employees should verify the latest instructions issued by the Income Tax Department and EPFO to ensure they use the correct form.
Disclaimer
This article is intended for general informational purposes only and should not be considered tax, legal or financial advice. The form requirements, TDS thresholds and tax rates mentioned are based on the information provided and have not been independently verified against the latest official notifications. Actual tax treatment may vary depending on individual circumstances and prevailing regulations. Readers should consult official EPFO and Income Tax Department guidance or a qualified tax professional before making decisions regarding PF withdrawals.