
Post Office savings schemes are designed for different financial goals. While some are meant to build wealth over a long period, others provide a fixed maturity amount or regular income.
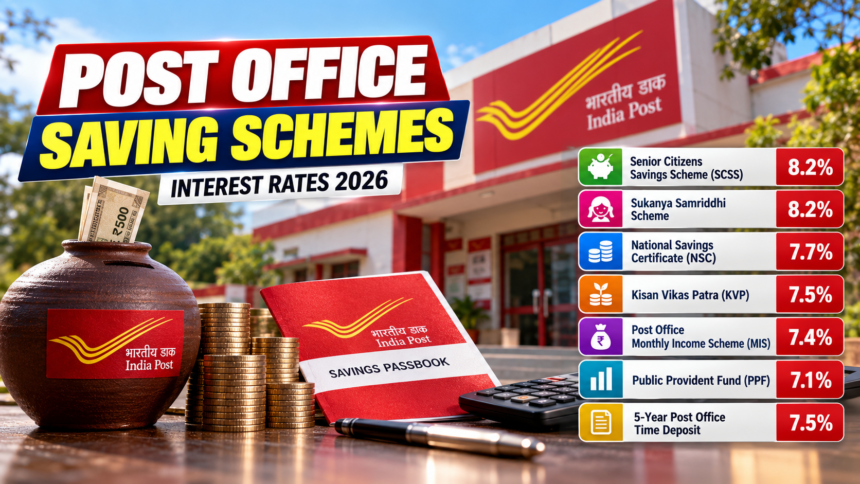
For the July 1 to September 30, 2026 quarter, the government has kept the interest rates on small savings schemes unchanged. At present, the highest interest rate of 8.2% is available under the Senior Citizens Savings Scheme (SCSS) and Sukanya Samriddhi Scheme. The Public Provident Fund (PPF) offers 7.1%, National Savings Certificate (NSC) 7.7%, Kisan Vikas Patra (KVP) 7.5% and the Post Office Monthly Income Scheme (MIS) 7.4%.
Choosing a scheme only because it offers a higher interest rate may not always be suitable. The right option depends on the purpose of the investment, whether you need regular income, want to build long-term savings, are investing for a child or are planning for retirement.
Kisan Vikas Patra: Double Your Investment
Kisan Vikas Patra (KVP) currently carries an interest rate of 7.5%. At this rate, the investment doubles in 115 months, or 9 years and 7 months.
For example, an investment of ₹1 lakh would become ₹2 lakh at maturity if the applicable rate remains as specified for the scheme.
The minimum investment starts at ₹1,000, and there is no maximum investment limit prescribed by the government. KVP can therefore be considered by investors looking to park a specific amount for a longer period.
However, the 9-year-and-7-month period is lengthy. Anyone who may need access to the money before maturity should understand the applicable withdrawal rules before investing.
Monthly Income Scheme and Senior Citizens Savings Scheme
The Post Office Monthly Income Scheme (MIS) currently offers an interest rate of 7.4% and provides interest payments every month.
An investment of ₹1 lakh at 7.4% would generate ₹7,400 in annual interest. On a simple calculation, this works out to approximately ₹617 per month.
The scheme has a 5-year tenure. The maximum investment limit is ₹9 lakh for an individual account and ₹15 lakh for a joint account. MIS can be suitable for investors seeking regular monthly income while keeping their principal invested.
For senior citizens, the Senior Citizens Savings Scheme (SCSS) currently offers 8.2% interest. It has a tenure of five years, with interest paid every quarter.
At an investment of ₹1 lakh, the annual interest at 8.2% would be ₹8,200. This translates to approximately ₹2,050 per quarter based on the annual calculation. Actual payouts are subject to the scheme’s rules.
The maximum investment allowed under SCSS is ₹30 lakh. Eligible senior citizens looking for regular income after retirement can consider the scheme based on their financial requirements.
PPF and National Savings Certificate
The Public Provident Fund (PPF) currently offers 7.1% interest and has a basic lock-in period of 15 years. Investors can contribute a minimum of ₹500 and a maximum of ₹1.5 lakh in a financial year.
Unlike KVP, PPF does not promise to double an investment within a fixed period. Instead, it is designed for disciplined, long-term wealth creation through regular investments.
If ₹1 lakh is invested once and the 7.1% interest rate remains unchanged for 15 years, it would grow to approximately ₹2.80 lakh through compound interest. However, PPF rates are reviewed by the government periodically, so this should only be treated as an illustration and not a guaranteed maturity amount.
PPF also offers tax benefits under the applicable rules, making its long-term structure and tax advantages important factors for investors to consider.
The National Savings Certificate (NSC) currently offers 7.7% interest and has a fixed five-year tenure. The minimum investment is ₹1,000, while there is no maximum investment limit.
Interest is calculated annually and is paid along with the principal at maturity. If ₹1 lakh is invested and the 7.7% rate remains unchanged throughout the five-year period, the maturity amount would be around ₹1.45 lakh, including approximately ₹44,900 in interest.
This calculation is only an illustration based on the current rate and does not account for any future changes in applicable rates.
Sukanya Samriddhi and 5-Year Time Deposit
The Sukanya Samriddhi Scheme is designed specifically for long-term savings for a girl child. It currently offers 8.2% interest.
The account can be opened with a minimum deposit of ₹250, while the maximum annual contribution is ₹1.5 lakh. The account matures 21 years after the date of opening.
Another option is the 5-Year Post Office Time Deposit, which works in a manner similar to a bank fixed deposit for investors looking to keep their money invested for a defined period. The five-year time deposit currently offers 7.5% interest.
These seven schemes have different purposes, investment limits, lock-in periods and payout structures. The current rates apply until September 30, 2026, and the government may revise them for the following quarter.
Investors should therefore check the latest official interest rates, eligibility conditions and scheme rules before putting their money into any Post Office savings scheme.
Disclaimer
This article is intended for general informational purposes only and should not be treated as financial or investment advice. Interest rates, maturity calculations, eligibility conditions and scheme rules may change according to government notifications. Investors should verify the latest official information and assess their financial requirements before making an investment decision.