
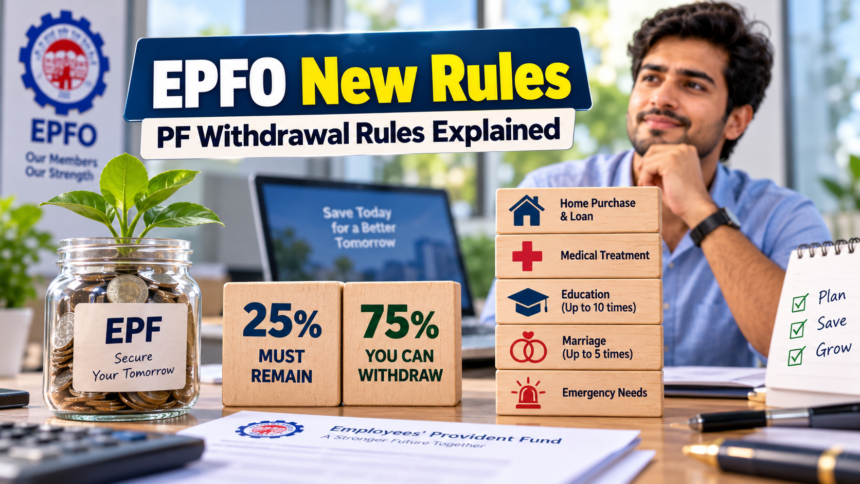
EPFO New Rules: Employees planning to withdraw money from their Employees’ Provident Fund (EPF) account should understand the latest withdrawal provisions before submitting a claim. The rules governing PF advance withdrawals have been revised, introducing changes in how much money members can access during their employment.
One of the key provisions is the requirement to keep 25% of the eligible PF balance in the account, while the remaining amount can be accessed subject to the applicable withdrawal conditions.
The revised framework also covers PF advances for important needs such as medical treatment, education, marriage, buying or constructing a house, home-loan repayment and other emergencies.
Here’s a detailed look at the new PF withdrawal rules and how much an EPFO member can withdraw for different purposes.
What Is the New 25% PF Withdrawal Rule?
Under the new framework, 25% of the accumulated PF amount has to remain in the account, meaning members can generally access up to 75% of the available funds, subject to the applicable rules.
The concept of “Eligible Member Balance” has also been introduced to determine the amount that can be considered for certain PF advances.
In simple terms, a portion of your retirement savings remains protected while the eligible amount can be used for specified financial requirements.
Example of the 25% PF Rule
Suppose your PF account has a total balance of ₹10 lakh.
- Total PF balance: ₹10 lakh
- Amount that must remain: ₹2.5 lakh
- Amount that can be withdrawn: ₹7.5 lakh
The actual amount available for withdrawal can, however, depend on the purpose of the advance and the conditions applicable to that category.
When Can You Withdraw Money From EPF?
EPFO provisions allow members to seek advances from their PF savings for certain specified requirements.
These include:
- Buying or constructing a house
- Purchasing land
- Repaying a home loan
- Home repairs
- Medical treatment
- Education
- Marriage
- Certain emergency or special circumstances
The amount that can be withdrawn varies depending on the reason for the claim.
PF Withdrawal for House Purchase, Construction or Home Loan
Members can use their EPF savings for certain housing-related requirements, including purchasing or constructing a house, home repairs and repayment of a housing loan.
Under the provisions described, an eligible member may be able to withdraw up to 100% of the eligible balance as an advance, provided the prescribed conditions are fulfilled.
The applicable eligibility requirements should be checked before submitting a claim.
How Much PF Can Be Withdrawn for Medical Treatment?
EPF advances can also be used to meet certain medical expenses.
If an employee or eligible family member requires medical treatment, the member may withdraw up to 100% of the eligible balance, subject to the applicable conditions.
This provision can provide financial support during significant medical emergencies when additional funds are required.
PF Withdrawal Rules for Education
EPF members can also access their PF savings for education-related expenses for themselves or eligible family members.
Under the stated rules, members can withdraw up to 100% of their eligible balance for this purpose.
However, there is a limit on how frequently this facility can be used. An EPFO member can make education-related advance withdrawals up to 10 times during their employment.
Once the maximum number of permitted withdrawals has been reached, another education advance cannot be claimed under this provision.
PF Withdrawal for Marriage
Money can also be withdrawn from the PF account for certain marriage-related expenses.
If the employee or an eligible family member is getting married, the member can withdraw up to 100% of the eligible member balance, subject to the applicable conditions.
This facility can be used a maximum of five times during the entire period of employment.
Can You Withdraw PF Money During an Emergency?
PF advances are also available for certain special or emergency financial requirements.
Under the provisions described, eligible members can access up to 100% of the eligible amount, while the mandatory portion that must remain protected in the account cannot be withdrawn.
Therefore, even when an employee faces financial distress, the retirement savings component is intended to retain a portion of the accumulated balance.
Is 12 Months of EPFO Membership Required?
Generally, an employee needs to have been an EPFO member for at least 12 months to qualify for certain PF advance withdrawals.
However, the eligibility period and other conditions can differ depending on the purpose of the withdrawal and the circumstances involved, including provisions applicable when an employee leaves employment.
Members should therefore check the specific conditions attached to their type of claim before applying.
What Is the 5-Year PF Withdrawal Rule?
The five-year service requirement is often misunderstood.
It is primarily relevant to the tax treatment of PF withdrawals and should not be confused with the basic eligibility for taking an advance from the EPF account during employment.
In other words, the five-year rule concerns whether tax may apply to a withdrawal in certain circumstances; it does not itself mean that an employee must complete five years before being allowed to take every type of PF advance.
Documents Required for Online PF Withdrawal
Members filing an online EPF claim generally need to ensure that their account information and KYC details are properly updated.
Common requirements include:
- Aadhaar-linked UAN
- Completed KYC
- Bank account linked with the UAN
- PAN, where applicable
Additional documentation may depend on the reason for the withdrawal.
For example, a medical claim may require relevant medical documents, while education-related claims could involve admission or educational records. Housing-related withdrawals may require documents connected with the property or loan.
When KYC and other details are properly updated, physical paperwork may not be required for many online claims. However, EPFO can request additional documents or information whenever necessary.
Have EPF Contribution and Interest Rules Changed?
The new withdrawal provisions do not change the method of EPF contribution or interest calculation.
The employee and employer contributions continue to be governed by the applicable EPF rules, while interest is credited according to the prevailing EPFO provisions.
The changes discussed above primarily concern access to PF savings through advance withdrawals.
Should You Withdraw Money From Your PF Account?
EPF is primarily designed to build a person’s long-term retirement savings. Although the rules provide access to funds for specific needs, frequent withdrawals can reduce the amount available when the employee eventually retires.
Therefore, members should consider withdrawing PF money only when there is a genuine financial requirement.
Employees who have completed five years of eligible service should also understand the tax implications before making a withdrawal.
The larger the PF corpus that remains invested until retirement, the greater the potential retirement savings.
EPFO PF Withdrawal Rules: Key Points at a Glance
| Rule | Key Detail |
|---|---|
| Minimum balance | 25% of the eligible PF balance to remain |
| General accessible portion | Up to 75%, subject to applicable rules |
| Medical withdrawal | Up to 100% of eligible balance, subject to conditions |
| Education withdrawal | Up to 100% of eligible balance |
| Education withdrawal limit | Maximum 10 times |
| Marriage withdrawal | Up to 100% of eligible balance |
| Marriage withdrawal limit | Maximum 5 times |
| Membership requirement | Generally 12 months for specified advances |
| 5-year rule | Primarily relevant to tax treatment |
| Online claim requirements | UAN, Aadhaar/KYC and linked bank account, with PAN where applicable |
Bottom Line
The revised EPFO PF withdrawal rules are important for employees who may need to access their retirement savings while still working. The new framework introduces greater clarity around the eligible member balance, withdrawal limits and specific purposes for which PF advances can be claimed.
However, PF is intended primarily as a retirement corpus. Before making a withdrawal, employees should carefully assess whether the money is genuinely required and understand any applicable eligibility, documentation and tax requirements.