
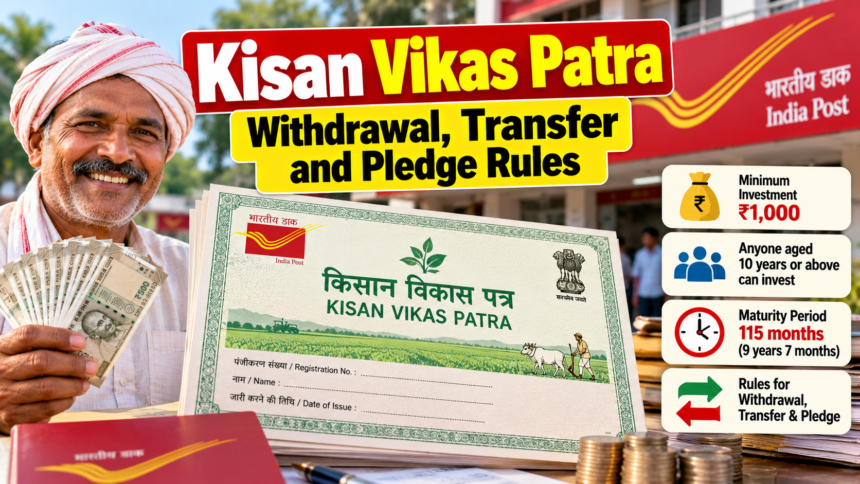
Kisan Vikas Patra (KVP) is a popular small-savings investment option offered through the post office. For existing investors, it is important to understand the rules governing premature withdrawal, transfer and pledging of the certificate.
The current maturity period of Kisan Vikas Patra is 115 months, or 9 years and 7 months. At the applicable interest rate, the invested amount doubles when the certificate reaches maturity. However, investors cannot withdraw the money whenever they want, as premature closure is permitted only under specified conditions.
Kisan Vikas Patra Investment Rules
The minimum amount required to invest in KVP is ₹1,000, and there is no maximum investment limit. Indian citizens aged 10 years or above can hold a Kisan Vikas Patra.
An adult can also open a KVP account on behalf of a minor. Once the minor reaches adulthood, the investment can be transferred to the account holder as per the applicable rules.
Aadhaar is required for KVP investment, while PAN details are required when the investment amount exceeds ₹50,000. For investments above ₹10 lakh, income-related documents may also be required.
When Can KVP Be Closed Before Maturity?
Kisan Vikas Patra cannot normally be closed before maturity whenever the investor chooses. Premature closure is allowed only in certain circumstances.
The certificate can be closed if the account holder dies. In a joint account, premature closure may be permitted following the death of one or both account holders. Closure can also take place under a court order or in cases involving seizure by the mortgagor.
If the KVP is closed prematurely, interest is paid at the applicable Post Office Savings Account rate rather than the full maturity benefit. After completing 2 years and 6 months, the principal amount along with the applicable interest is paid according to the prescribed rules.
KVP Can Also Be Pledged as Security
Kisan Vikas Patra can be used as security against a secured loan. For this, the investor needs to complete the required form at the post office and submit an acceptance letter from the concerned institution.
Under the specified conditions, a KVP can be pledged in favour of the RBI, government or scheduled banks, cooperative banks or societies, government companies, local authorities and housing finance companies.
Rules for Transferring Kisan Vikas Patra
KVP can be transferred to an eligible person, nominee or legal heir in certain circumstances, particularly after the death of the original account holder.
In a joint KVP account, the certificate may be transferred to the surviving account holder after the death of one of the holders. Transfer may also be permitted through a court order or when the KVP has been pledged as security.
Disclaimer
This article is intended for general informational purposes and is based on the details provided in the source material. Kisan Vikas Patra rules, interest rates, documentation requirements and conditions for premature closure or transfer may be revised from time to time. Investors should verify the latest applicable rules with the post office or official government sources before taking any financial decision.